
Online marketplaces and gig-economy platforms are built to connect customers, service providers, freelancers, vendors and sellers in a single digital ecosystem. Whether facilitating services, products or subscriptions, those transactions depend on payment infrastructure that works reliably as the platform grows.
When it comes to marketplace payments, a similar story emerges across platforms: in the early days, payment functionality sits quietly in the background, doing its job. Then the marketplace grows, and so does the challenge of making sure everyone has their money.
Whether you're running a task marketplace similar to Airtasker, a freelancer platform, an automotive marketplace like carsales, an eCommerce marketplace connecting buyers and sellers or a niche service marketplace, the same payment challenges often emerge. Collecting money is the first step, and often the easy part. Reconciling it and managing seller payouts brings an added layer of complexity, and often one that traditional payment providers may not effectively support.
This article explores some of the biggest marketplace payment infrastructure challenges and shares the possible solutions for faster, more reliable and more accurate transactions.
For marketplaces, collecting funds is only half the problem
Most payment platforms are built to solve the first half of the equation in a traditional buy-and-sell environment. Customers pay with a card, PayID or bank transfer, and the funds land in the merchant’s account.
But marketplaces don’t provide a simple retail or service-provider transaction. It's a two-sided flow, and every dollar collected from a customer eventually needs to be split, tracked and paid out again, to a tasker, a freelancer, a vendor or a subscriber's downstream service.
If your marketplace platform’s payment infrastructure only handles the collection side effectively, there’s going to be a lot of pressure on your financial admin team to ensure funds are then distributed correctly.
Marketplace payments: Reconciliation can breakdown as you scale
At low volumes, matching a payment to the person who sent it and the person who needs to receive funds when something goes wrong can be manageable. At scale, it can become a full-time job, sometimes requiring multiple headcounts. A platform processing thousands of transactions a week often can't rely on customers entering the right reference number, and it generally can't afford to have finance staff manually matching bank statements against orders.
This is where many payment platforms hit a wall.
Incorrect or missing references mean payments can't be automatically attributed, so someone has to chase them down. Multiply that across thousands of taskers, freelancers or sellers, and the admin burden can scale faster than the business does.
Delayed marketplace payouts can erode trust fast. A freelancer who waits three days to get paid for a completed job might not stay loyal to a platform for long. In a market where switching is easy, payout speed and accuracy are necessary to maintain a competitive advantage.
There are also fraud and compliance risks to take into account. Every payout is a point where funds leave the business, so platforms need visibility for audit trails and fraud protection.
The payment features you need as your marketplace grows
As transaction volumes increase, many marketplaces discover that generic payment processing tools may not provide the visibility, automation and control required to manage funds at scale.
Modern marketplace payment infrastructure needs to support both collections and seller payouts while reducing manual administration.
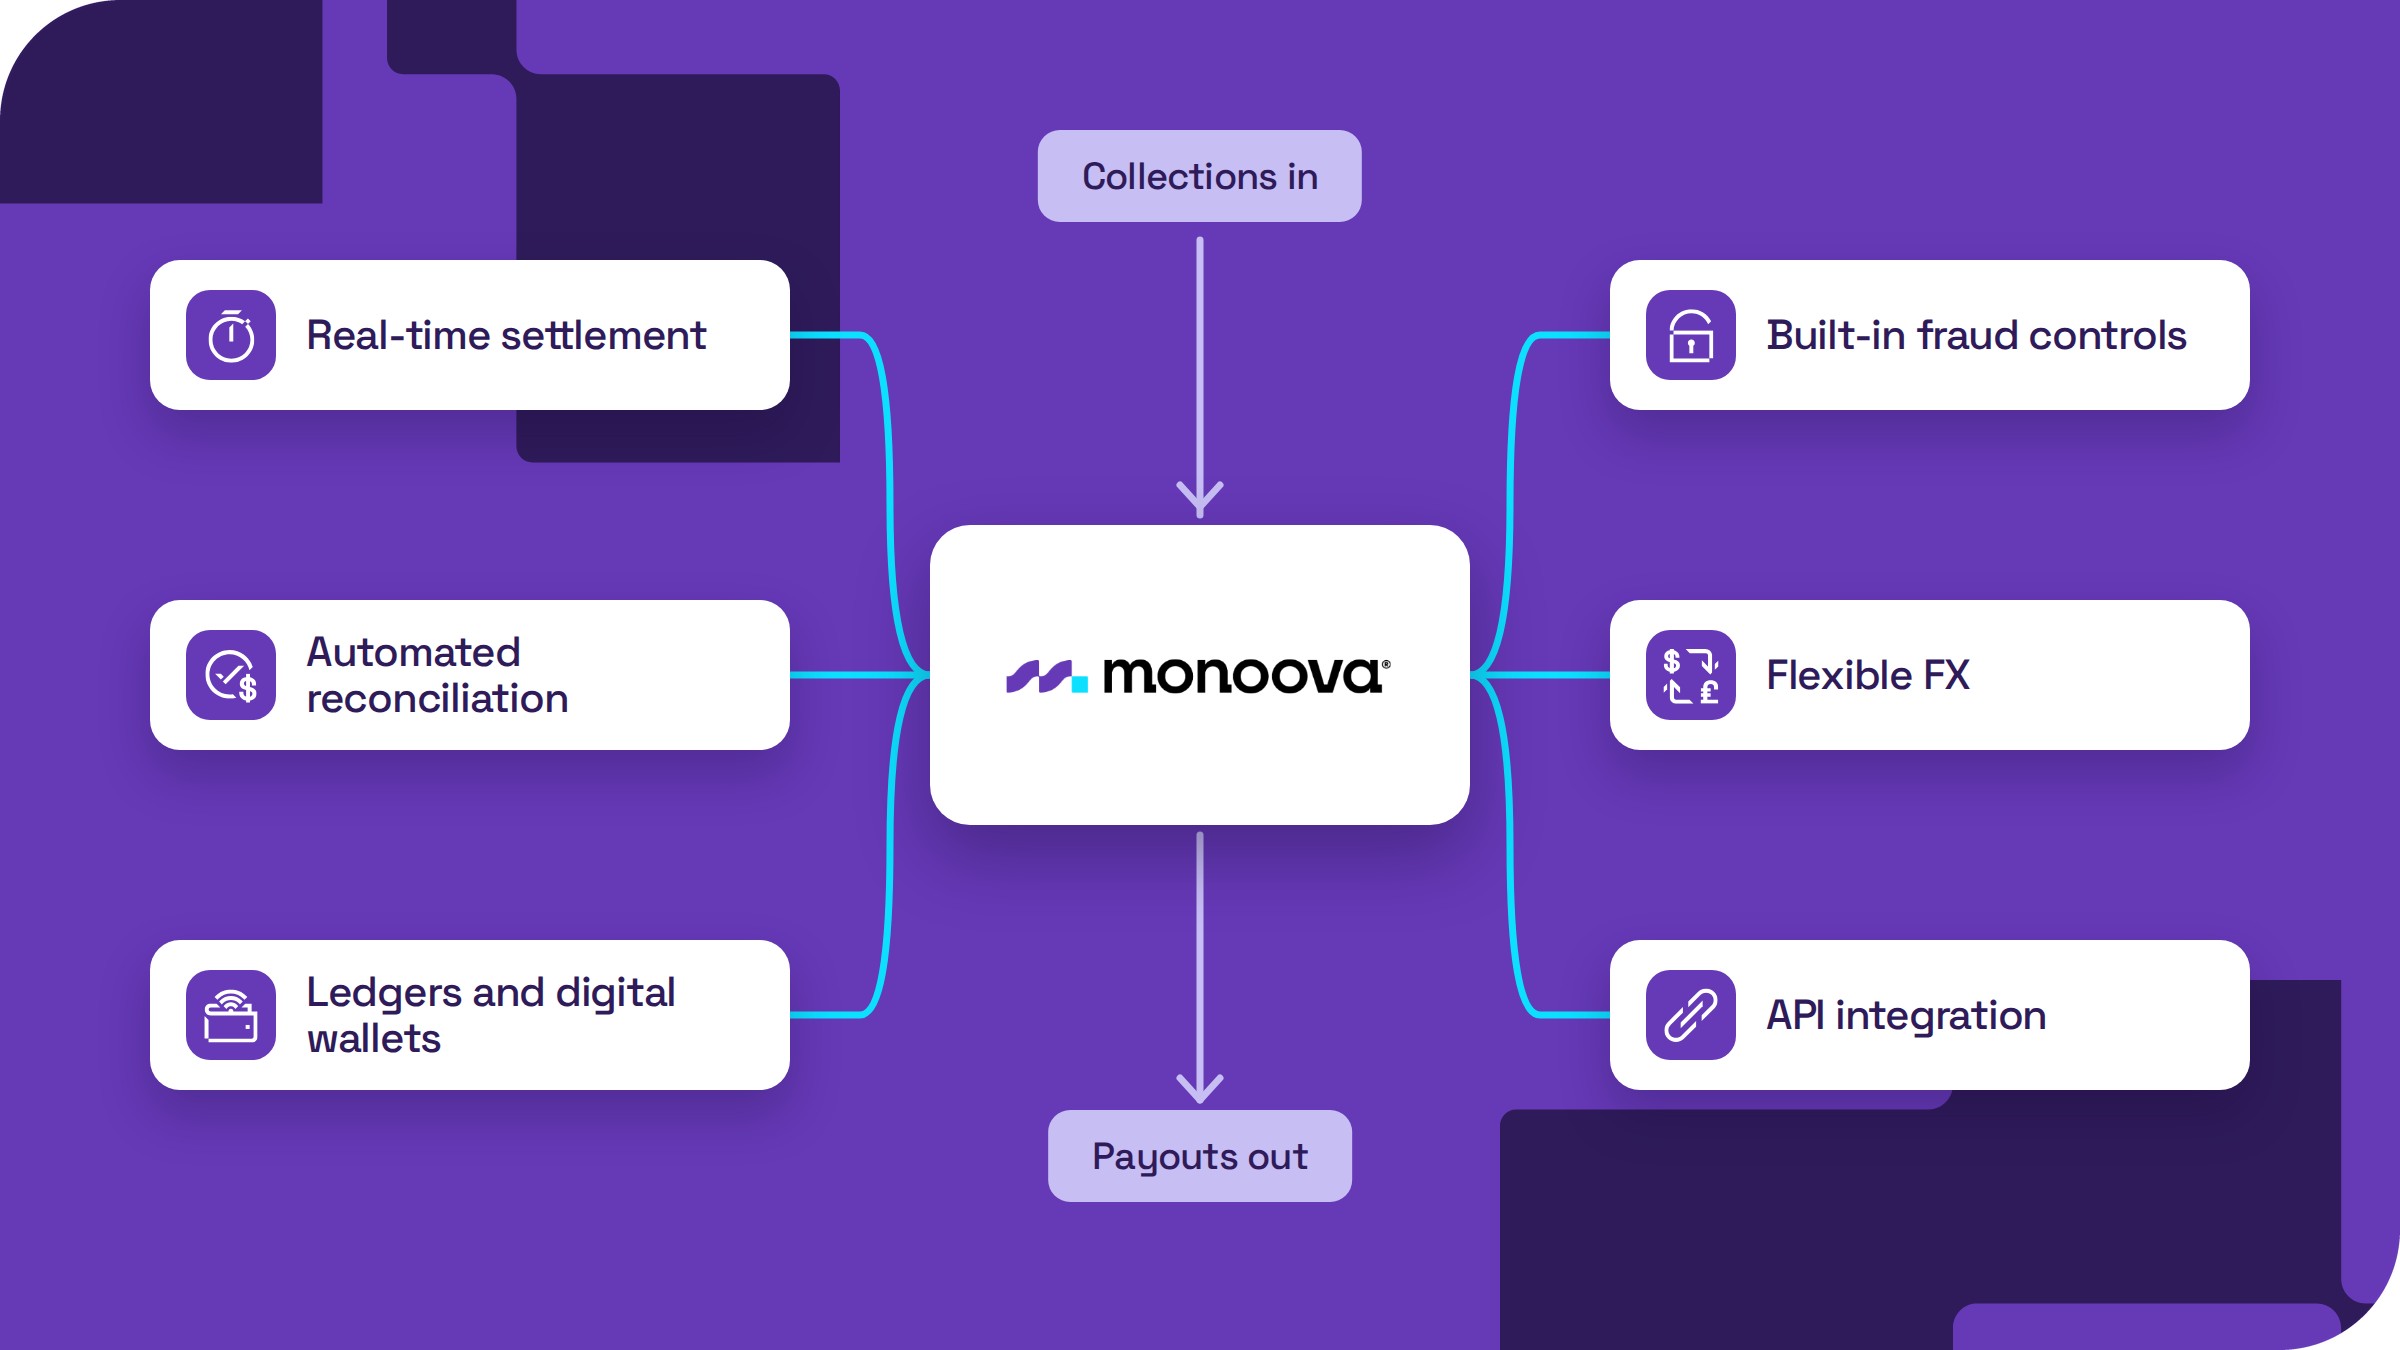
The following are mission-critical for modern marketplaces:
- Real-time settlement. Traditional bank transfers can take two to three days. Platforms built on real-time rails like the NPP settle funds in seconds, on both the collection and payout side.
- Automated reconciliation. Virtual accounts and PayID can assign a unique identifier to each seller, freelancer or transaction, helping automate payment matching and reduce manual reconciliation work.
- Ledgers and digital wallets. Managing balances for thousands of sellers or subscribers generally requires purpose-built infrastructure.
- Built-in fraud controls. As payout volumes grow, so does exposure. Look for infrastructure with fraud controls designed for two-sided payment flows.
- Flexible FX. If your providers or freelancers are based overseas, wholesale exchange rates and fast settlement can help improve user experience while keeping costs under control.
- Flexible integration. A payments partner should integrate with your existing platform through an API, which can help limit the need to rebuild workflows or retrain teams.
Previously, achieving these capabilities often meant an expensive and time-consuming in-house build or relying on a patchwork of providers. Monoova can help to bring everything together with a plug-and-play solution.
Solving the challenges of marketplace seller payouts
Monoova is built to handle both sides of the payment equation for marketplaces and manage payouts as well as collections.
carsales is one example of a platform that has scaled its payment operations with Monoova, moving away from manual processes toward more automated funds transfers that are built to keep pace with growth. As a leading Australian automotive marketplace, carsales was able to explain its key challenges, then work with the Monoova team to introduce ledger capabilities designed to give its users a better sense of security and control.
As your online marketplace scales, marketplace payment infrastructure becomes increasingly important. The ability to collect funds, automate reconciliation and manage seller payouts efficiently can help improve platform usability, reduce operational overhead and support sustainable growth.